
Last updated: October 2026 · 3 min read
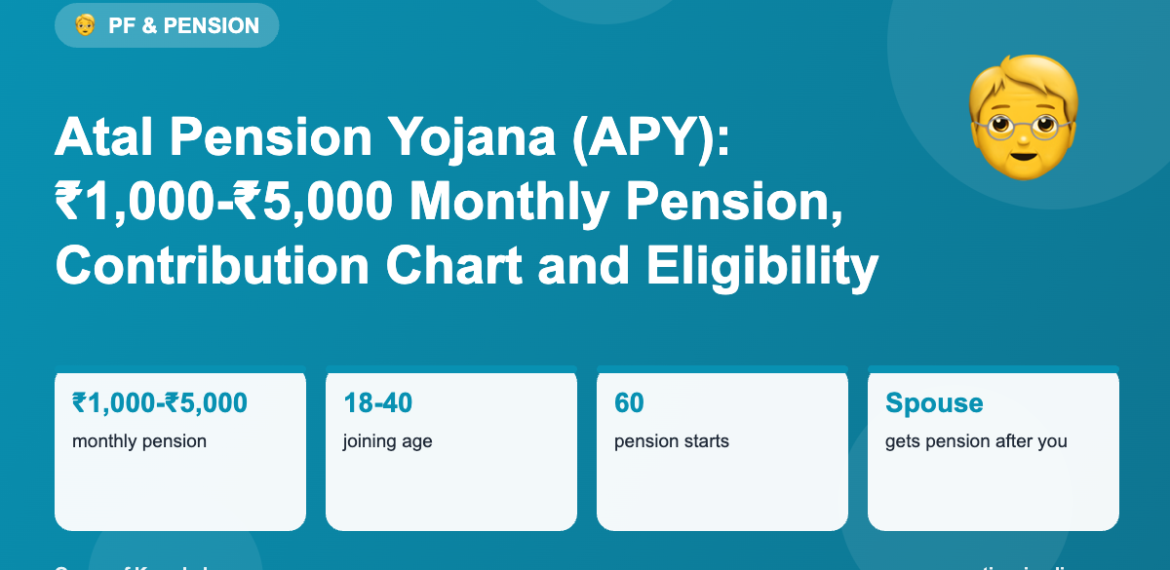
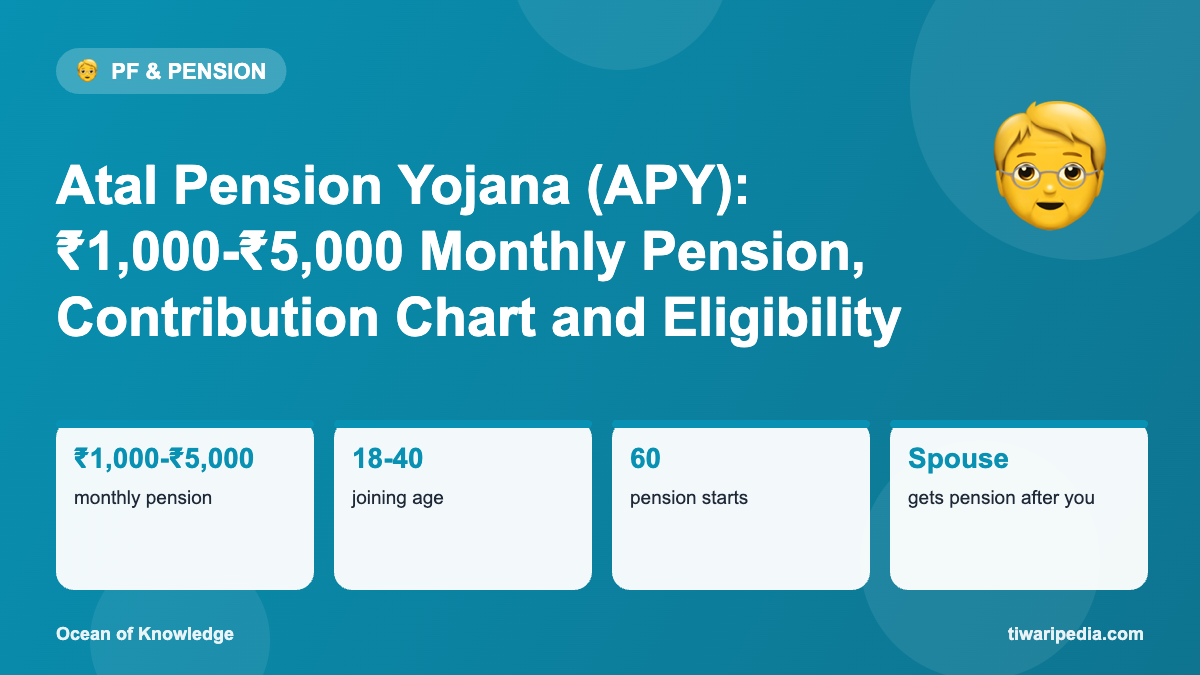
Atal Pension Yojana (APY), launched in 2015 and administered by PFRDA, offers a guaranteed monthly pension of ₹1,000 to ₹5,000 from age 60 to workers, especially in the unorganised sector. The earlier you join, the lower your contribution.
Eligibility
- Indian citizens aged 18 to 40 years.
- Must have a savings bank or post office account.
- From 1 October 2022, people who are or have been income taxpayers cannot join.
- Contributions continue until age 60.
Monthly contribution chart (selected ages)
| Joining age | ₹1,000 pension | ₹2,000 pension | ₹3,000 pension | ₹4,000 pension | ₹5,000 pension |
|---|---|---|---|---|---|
| 18 | ₹42 | ₹84 | ₹126 | ₹168 | ₹210 |
| 25 | ₹76 | ₹151 | ₹226 | ₹301 | ₹376 |
| 30 | ₹116 | ₹231 | ₹347 | ₹462 | ₹577 |
| 35 | ₹181 | ₹362 | ₹543 | ₹722 | ₹902 |
| 40 | ₹291 | ₹582 | ₹873 | ₹1,164 | ₹1,454 |
Monthly contributions as per the official APY chart; quarterly and half-yearly options are also available.
Benefits
| Event | Benefit |
|---|---|
| At 60 | Guaranteed monthly pension for life |
| On subscriber’s death after 60 | Spouse receives the same pension for life |
| After death of both | Nominee receives the accumulated corpus (₹1.7 lakh to ₹8.5 lakh depending on pension chosen) |
| Death before 60 | Spouse can continue contributions or claim the corpus |
How to join
- Visit your bank or post office where you have a savings account, or use your bank’s net banking/app.
- Fill the APY registration form with Aadhaar and mobile number.
- Choose pension amount and contribution frequency.
- Contributions are auto-debited; keep enough balance to avoid penalties.
Things to keep in mind
The pension amount is fixed and does not rise with inflation, so ₹5,000 in 30 years will buy much less than today. APY works best as a basic safety net alongside other savings like PPF or NPS.
Frequently asked questions
Can I increase my APY pension later?
Yes, you can upgrade or downgrade the pension amount once a year, during April.
What happens if I miss contributions?
A small penalty applies; the account may be frozen or closed after prolonged default.
Is APY pension taxable?
Pension received is taxable as income, though most APY subscribers fall below taxable limits.
Keep exploring
This article is for general information, not financial, tax or legal advice. Rates, limits and rules change; always confirm on the official website or with a qualified advisor before you act. Spotted something that needs updating? Let us know.