
Last updated: October 2026 · 3 min read
Life insurance policies come in many shapes, and agents often sell those that earn higher commissions. Understanding the main types helps you pick what actually fits your needs: protection, savings, or both.
Main types compared
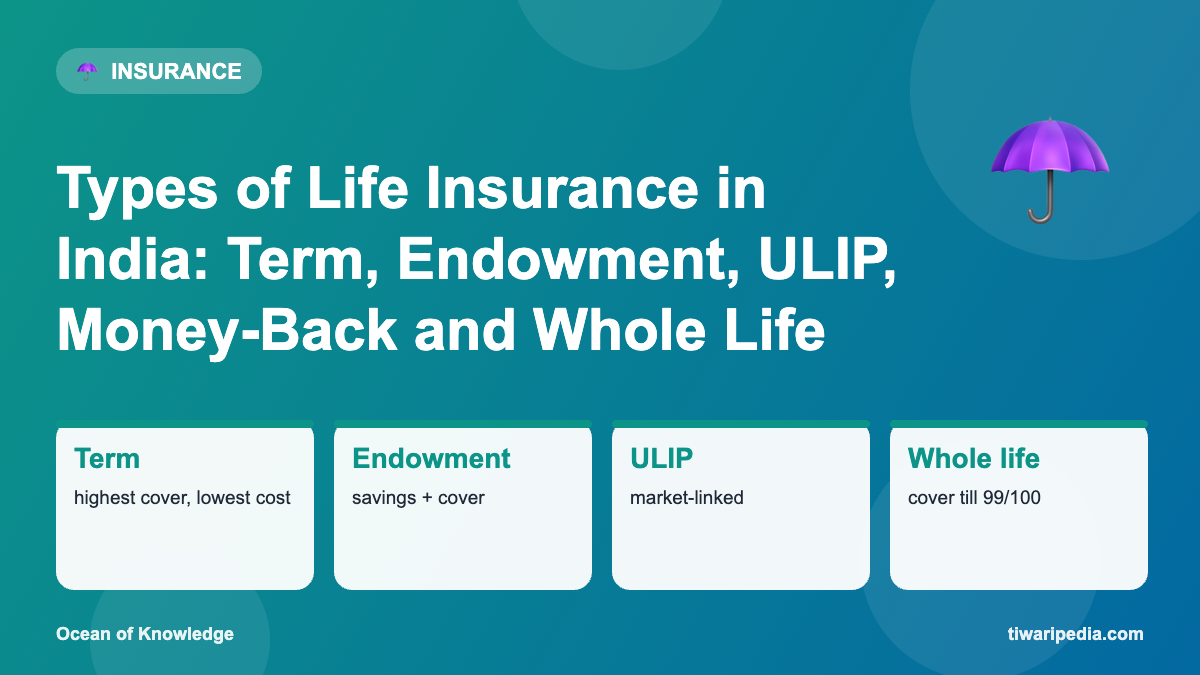
| Type | What it offers | Pros | Cons |
|---|---|---|---|
| Term insurance | Pure life cover for a period | Very high cover at low premium | No maturity benefit (unless return-of-premium) |
| Endowment | Cover plus guaranteed or bonus-based maturity amount | Forced savings, guaranteed payout | Low returns, low cover |
| Money-back | Periodic payouts during the term plus cover | Regular cash flow | Lower returns and cover |
| ULIP | Market-linked investment plus cover | Choice of equity/debt funds, 5-year lock-in | Charges, market risk, low cover |
| Whole life | Cover up to age 99/100 | Legacy planning | Expensive premiums |
| Pension/annuity plans | Regular income after retirement | Guaranteed income options | Annuity income taxable, low flexibility |
The golden rule: separate insurance and investment
For most people, the most efficient approach is to buy adequate term insurance for protection and invest separately through PPF, mutual funds or NPS for growth. Combined products often give both lower cover and lower returns.
When traditional plans can make sense
- If you want guaranteed returns and lack discipline to save.
- For specific goals with very low risk tolerance.
- For legacy and estate planning (whole life).
Questions to ask before buying
- What is the sum assured compared with my income?
- What is the guaranteed maturity amount and IRR (internal rate of return)?
- What are the charges and surrender penalties?
- Is the premium affordable for the full term?
- What is the insurer’s claim settlement record?
Free-look period and mis-selling
You can return a new policy within the free-look period (IRDAI extended it to 30 days in 2024) if it does not suit you, and get a refund minus some charges. Report mis-selling to the insurer’s grievance cell and then to the IRDAI Bima Bharosa portal.
Frequently asked questions
Which life insurance is best?
For pure protection, term insurance is usually best value; other plans suit specific savings or legacy needs.
Are ULIPs good investments?
Modern ULIPs have lower charges than before, but compare them with term insurance plus mutual funds before buying.
Is LIC maturity amount taxable?
It depends on premium size and policy date; policies with very high premiums may have taxable maturity proceeds. Check current rules.
Keep exploring
This article is for general information, not financial, tax or legal advice. Rates, limits and rules change; always confirm on the official website or with a qualified advisor before you act. Spotted something that needs updating? Let us know.